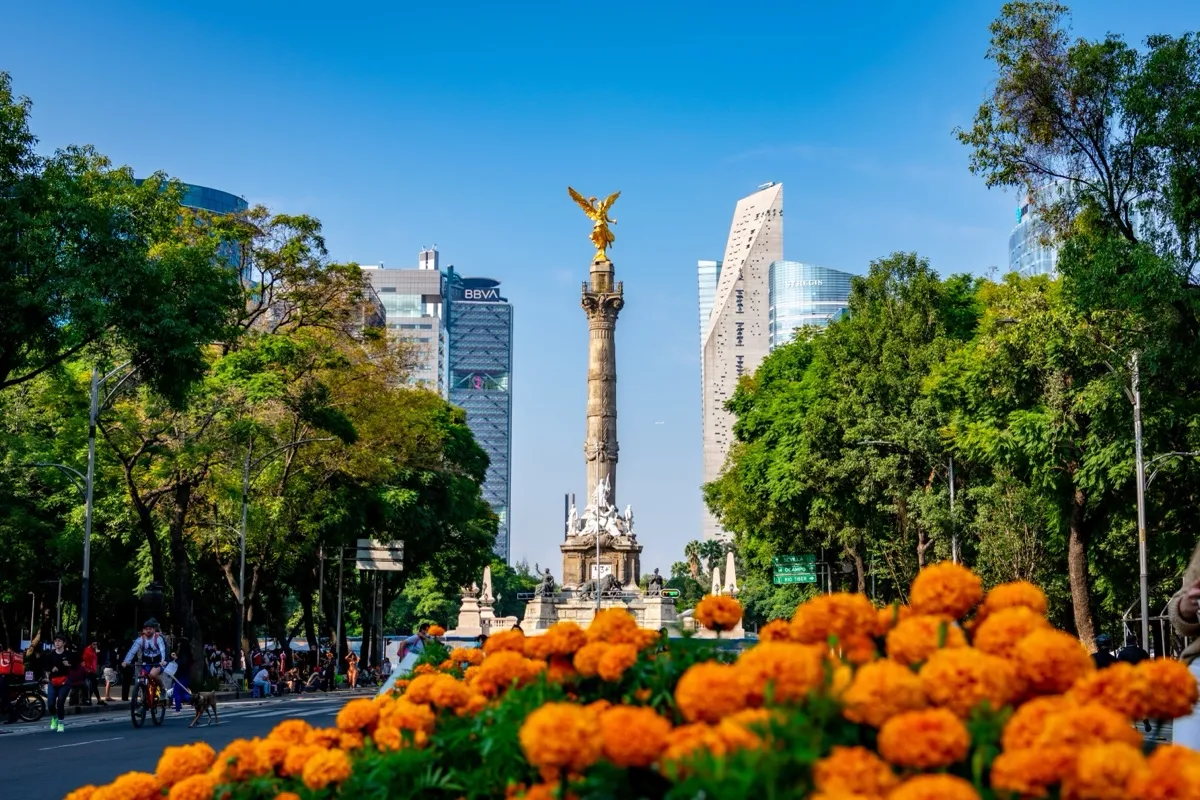
 Photo: Oscar Dominguez, PexelsPhoto: Oscar Dominguez, Pexels
The reform limits deductions, loss offsets, interest and withholding, affecting corporate cash tax planning for companies operating in Mexico from 2027.
Mexico published the Decree issuing the Federal Revenue Law for Fiscal Year 2027 and the Decree amending the Income Tax Law in the Official Gazette of the Federation on 13 November 2026. Regfollower+2 The 2027 Economic Package introduces corporate deduction and tax loss limits, changes to interest deductions and withholding taxes, digital platform obligations, VAT measures and accelerated investment deductions. Regfollower The reform does not change Mexico's corporate income tax rate but focuses on the timing and availability of deductions and tax losses. KPMG A general limitation applies to Mexican legal entities with annual taxable revenue exceeding MXN 50 million and a tax profit for the year, capping deductions at 96.67% of taxable revenue. Baker McKenzie Prior-year net operating losses may offset only 50% of the tax profit generated in a year, and disallowed amounts may be carried forward for up to 20 years. Baker McKenzie The enacted provisions are substantially consistent with the proposals submitted to Congress on 8 September 2026, with certain limited modifications. Baker McKenzie+1
The Federal Executive submitted the 2027 Economic Package to Congress on 8 September 2026, proposing amendments to the Income Tax Law, Federal Revenue Law, Customs Law and Federal Duties Law. Regfollower President Claudia Sheinbaum Pardo promulgated both bills on 10 November 2026. Regfollower The reform may change the Mexican cash tax profile of affected companies beginning in 2027. KPMG
Most provisions take effect on 1 January 2027. Regfollower+2 Select downstream fuel enforcement measures enter into force on 1 July 2027. Regfollower
Photo: Oscar Dominguez, Pexels Photo: Sacramento Bee
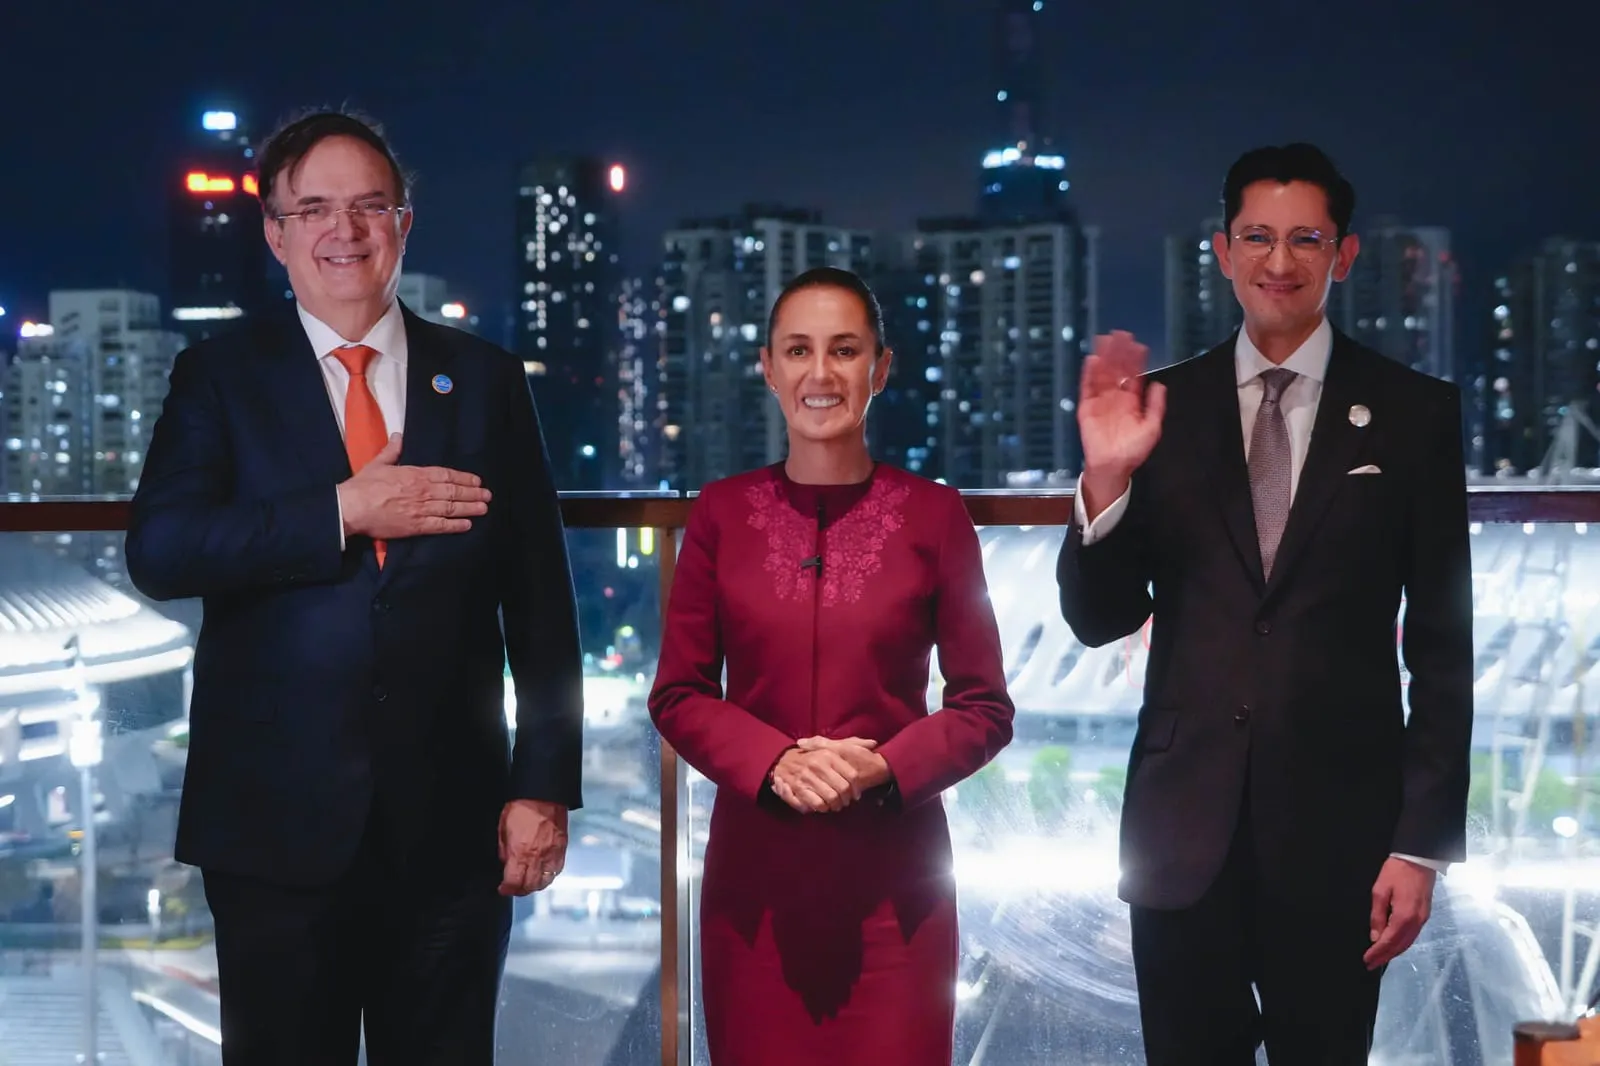 Photo: International Business Times